E‑Mart’s Stock Slumps Amid Market Volatility: A Call for Strategic Reorientation
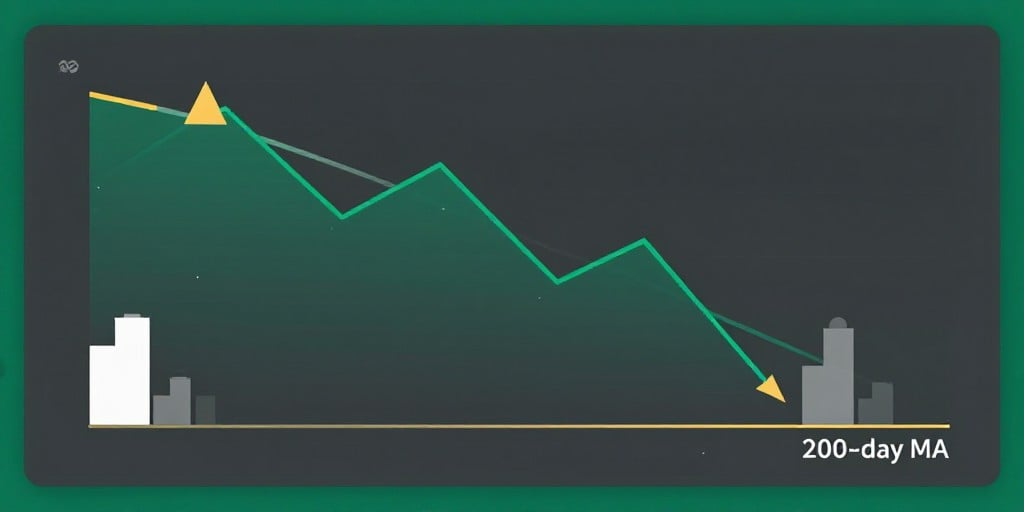
E‑Mart Inc. (ticker 139480.KS) closed the trading session on Saturday, 24 November 2026, down 2.74 % to KRW 69,500. With a market capitalization hovering around KRW 2 trillion, the hypermarket chain’s shares are now trading at a level that underscores the mounting pressure from a broader industry downturn.
Key Metrics
| Metric | Value |
|---|---|
| Current Price | KRW 69,500 |
| 24‑hour Volume | KRW 5.6 bn |
| Supply of Shares | 27.6 mn |
| 200‑day SMA | KRW 87,580 |
| 52‑week High | KRW 136,400 (02/11/2026) |
| 52‑week Low | KRW 68,100 (10/15/2026) |
| Market Cap | KRW 2 trillion |
The stock has fallen 0.56 % since the previous month‑end, a modest decline that masks the deeper structural issues facing the retail sector. While the 200‑day simple moving average sits comfortably above the current trading level, the sharp 52‑week swing from KRW 136,400 to KRW 68,100 reveals a market that has grown increasingly skeptical of E‑Mart’s growth narrative.
Comparative Performance of Peer Stocks
- SL Corporation (005850.KS) – Up 0.2 % at KRW 49,400; market cap KRW 2.3 trillion; P/E 6.08.
- Lotte Chemical (011170.KS) – Down 4.2 % at KRW 48,150; market cap KRW 2.2 trillion.
- BGF Retail (282330.KS) – Up 0.67 % at KRW 131,900; market cap KRW 2.3 trillion; P/E 11.13.
These figures paint a stark picture: while some peers are modestly buoyant, others are languishing, and E‑Mart’s performance is lagging behind the group’s median trajectory.
Why the Drop Matters
- Profitability Concerns – E‑Mart’s aggressive expansion into online marketplaces and specialty shops has yet to translate into a sustainable profit margin.
- Competitive Pressure – The rise of e‑commerce giants and discount retailers erodes margins across the sector, forcing traditional hypermarkets to lower prices and cut costs.
- Investor Sentiment – A falling share price signals waning confidence in the company’s ability to deliver value in a rapidly evolving retail landscape.
The Call for Strategic Reorientation
E‑Mart’s diversified portfolio—ranging from Emart discount stores to niche outlets like Electromart and Molly’s Pet Shop—suggests a willingness to experiment. However, without a coherent strategy that aligns these ventures under a unified growth engine, the company risks becoming a “jack of all trades, master of none.”
- Consolidate Core Brands – Prioritize the most profitable segments and consider divesting underperforming stores.
- Accelerate Digital Integration – Leverage its Emart Mall and Traders Mall platforms to capture the growing online consumer base.
- Strengthen Supply Chain Resilience – Invest in logistics and inventory management to reduce costs and improve customer satisfaction.
Conclusion
E‑Mart’s recent decline is not merely a short‑term fluctuation; it is a symptom of deeper strategic misalignments and a market that demands sharper focus. Investors and stakeholders alike must now confront the uncomfortable reality that the current trajectory will not sustain shareholder value. A decisive recalibration—anchored in digital transformation, operational efficiency, and a laser‑focused brand strategy—is imperative if E‑Mart hopes to reclaim its former market dominance.